
Why Gaming Operators Are Switching to Single-API Disbursements
High-volume payouts should not require a high-complexity payment stack. Yet many gaming operators, loyalty programmes, employers, NGOs, insurers and stokvels still manage separate integrations for bank payments, bill payments and value-added services.
A single-API disbursement platform offers a simpler model. Instead of building and maintaining several payment connections, an organisation can use one integration to manage multiple services. This can reduce technical work, simplify operations and help teams launch new payout options faster.
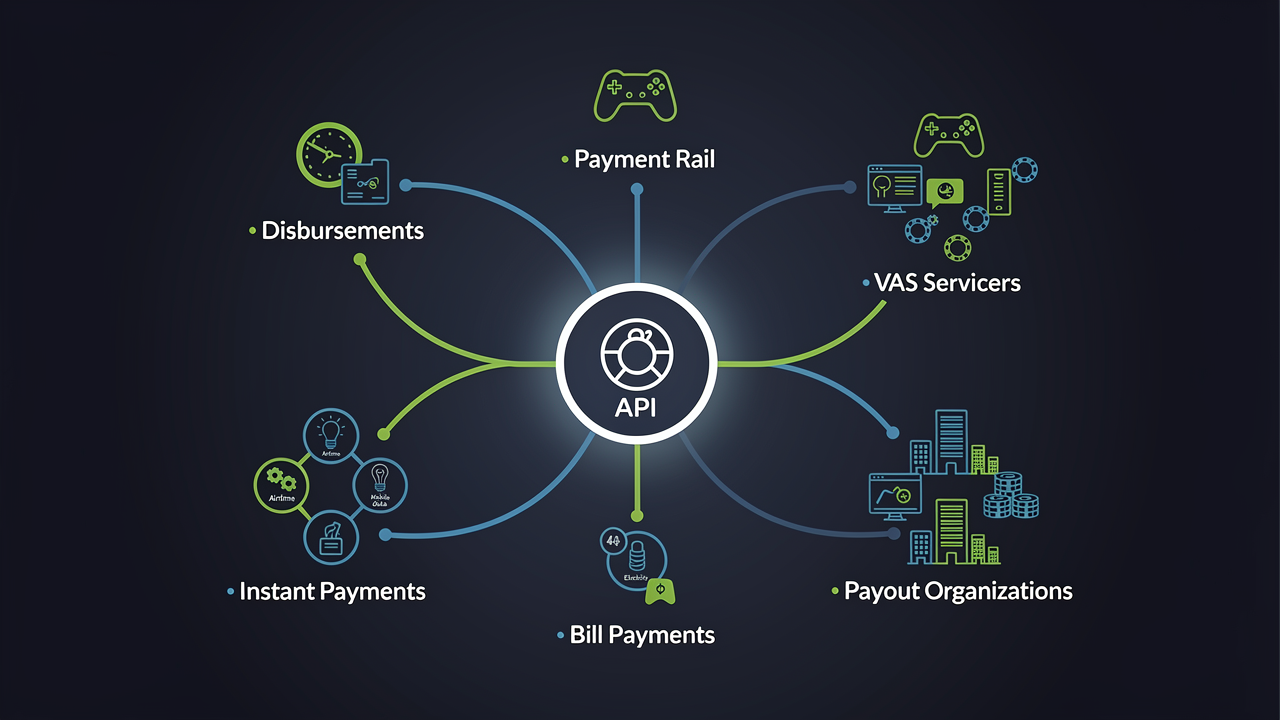
MyMoolah provides a single API for disbursements, instant payments, bill payments and value-added services such as airtime, data and electricity. It is a digital wallet and treasury platform, not a bank. (Source: MyMoolah business profile)
Information current as at 2 November 2026. MyMoolah is a registered Third-Party Payment Provider (TPPP) sponsored by The Standard Bank of South Africa Limited. Wallet limits apply.
The payout problem: why multi-bank integrations cost more to manage
A direct connection to one bank may appear straightforward. The challenge grows when an organisation needs to support several payment methods, banking relationships or services.
Each additional integration may need its own technical build, testing process, operating rules and support workflow. Internal teams must monitor different interfaces and investigate failures across separate systems. When an interface changes, the organisation may also need to update and retest that connection.
This fragmented approach can create several operational pressures:
- More integration work for product and engineering teams.
- Separate payment and service workflows to monitor.
- More points at which a transaction or system process can fail.
- Longer implementation work when adding new payout or value-added services.
- More complex support and reconciliation processes.
The exact cost of this complexity will differ by organisation. However, decision-makers should consider the full operating cost, not only the transaction fee. Development time, maintenance, support and change management all affect the business case.
What is a single-API disbursement platform?
An application programming interface, or API, lets different systems exchange instructions and information. A single-API platform gives an organisation one integration through which it can access a wider set of payment services.
With MyMoolah, that service set includes disbursements, instant payments, bill payments and value-added services. This removes the need to build a separate integration for each of those functions. (Source: MyMoolah business profile)
For a gaming operator, this could mean connecting its existing platform to one payment infrastructure partner rather than managing several stand-alone service connections. The same model can support loyalty rewards, employer payments, insurance disbursements, NGO payments and other high-volume use cases.
How MyMoolah’s single API simplifies gaming payouts
A gaming payout platform must serve two groups: the operator managing the transaction and the customer who needs practical access to funds. A unified API can simplify the operator’s side by bringing payment functions into one integration.
This approach may help an operator:
- Reduce the number of integrations it has to build and maintain.
- Use a consistent technical connection across supported services.
- Add instant payment and wallet-based payout options without creating a separate platform for each service.
- Centralise more of the payment workflow with one infrastructure partner.
- Free internal technical teams to focus on the operator’s core product.
These are operational benefits rather than guaranteed savings. Each operator should compare its current integration, support and transaction costs with the proposed single-API model.
Beyond payouts: add value-added services through the same API
A payout does not always need to end with a cash transfer. MyMoolah’s API also supports airtime, data, electricity and bill payments. (Source: MyMoolah business profile)
This gives organisations more ways to structure a service. A loyalty programme could combine a reward payment with access to airtime or electricity. An employer could use the same integration for disbursements and selected value-added services. A gaming operator could make supported services available without developing an independent connection for every provider.
The strategic value is flexibility. Once the single integration is in place, the organisation has a broader service base on which to design relevant customer journeys. Whether that improves engagement or revenue will depend on the organisation’s offering, pricing and customer adoption.
Illustrative use case: stokvels and gaming pools
Consider a stokvel or gaming pool that needs to distribute funds to several members. Under a fragmented model, the administrator may need to coordinate different payment channels and then manage separate queries when payments do not follow the same process.
Under a single-API model, the organisation’s platform could send supported disbursement instructions through one integration. Members using the wallet-based option could also cash out with a bank-issued cardless withdrawal PIN, where available.
This is an illustrative workflow, not a reported customer case study. Its purpose is to show how one technical connection can support both central payout management and practical cash access options.
Compliance and security: why TPPP registration matters
Organisations may be cautious about using a non-bank payment provider, particularly when payments are frequent or high in volume. The correct starting point is to understand the provider’s role and regulatory status.
MyMoolah is a registered Third-Party Payment Provider (TPPP) sponsored by The Standard Bank of South Africa Limited. This enables MyMoolah to provide compliant disbursement services. (Source: MyMoolah business profile)
MyMoolah is not a bank. It does not offer lending, credit or deposit insurance. It operates as a digital wallet and treasury platform. (Source: MyMoolah business profile)
TPPP registration and bank sponsorship provide important regulatory context, but organisations should still complete their own technical, compliance, fraud and operational assessments before implementation.
Cost comparison: look beyond a single transaction fee
A fair comparison between a single API and direct banking integrations should include both visible and less visible costs. Decision-makers can assess:
- Initial development and testing costs.
- Ongoing maintenance for each integration.
- Internal support and reconciliation work.
- The cost of adding bill payments or value-added services later.
- Monthly account and applicable transaction fees.
- Customer access to supported deposit and withdrawal channels.
Free between MyMoolah wallets, up to R100,000, within your verification (KYC) limits. Fees apply to bank transfers and cash withdrawals. MyMoolah currently charges per transaction, with no monthly subscription fee. For operator payouts: pay into MyMoolah wallets instantly and free of charge, from your funded float, within each recipient’s verification (KYC) limits.
These fees cover different transaction types and should not be treated as interchangeable. Organisations should model their own expected volumes and transaction mix before comparing the total cost with their current banking arrangements.
How to get started with MyMoolah’s disbursement API
Start by documenting the services and payment routes your organisation currently uses. Identify how many integrations are involved, what they cost to maintain and where support or reconciliation work is concentrated.
Next, define the services required from a future platform. These may include disbursements, instant payments, bill payments, airtime, data, electricity and wallet-based cash access. Your technical and compliance teams can then evaluate how MyMoolah’s single API fits the required workflow.
The strongest business case will compare total operating effort, customer access and service flexibility—not transaction pricing alone.
Ready to offer wallet services with disbursements + VAS via a single API integration? Contact partnerships@mymoolah.africa