
Information current as at 2 November 2026. MyMoolah is a registered Third-Party Payment Provider (TPPP) sponsored by The Standard Bank of South Africa Limited. Wallet limits apply.
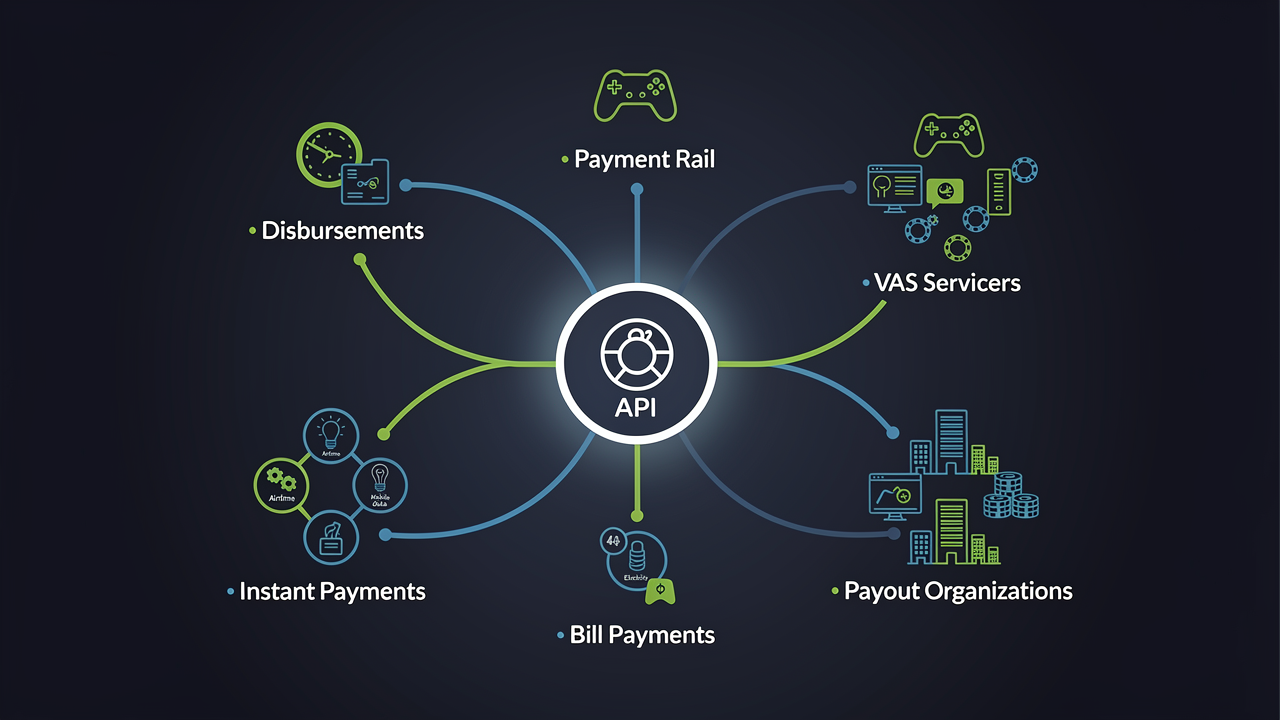
Stokvel administrators can digitise member payouts without removing the flexibility that cash provides. With one MyMoolah API integration, a stokvel or fintech partner can disburse money to digital wallets, offer airtime, data and electricity, and create a commission-earning opportunity from these value-added services.
This model can reduce manual work, limit cash handling and make reconciliation easier. It also gives members different ways to use or access their money. The result is a simpler operating model with the potential for added revenue.
The stokvel opportunity: why digitisation matters
Stokvels are built on shared trust and clear rules. However, the process used to collect, manage and pay out money may still rely heavily on cash or individual bank transfers. This can create extra work at the point when administrators need to distribute funds to many members.
Digital payouts provide an alternative. Instead of preparing cash or processing separate transfers, an administrator can use a connected disbursement service to pay members into digital wallets. MyMoolah’s wallet and disbursement API supports instant stokvel payouts without cash or bank transfers.1
Digitisation does not have to mean forcing every member to stop using cash. MyMoolah offers cash withdrawals with a bank-issued cardless PIN through a national cash-out network of ATMs and retail points, in both the formal and informal sectors, so members can still get cash when they need it.1 This creates a practical bridge between familiar cash-based behaviour and digital financial services.
The challenge of manual payouts: time, cost and risk
Manual payouts can place a heavy burden on stokvel administrators. Common operational issues include:
- Preparing and counting cash for distribution.
- Processing payments one member at a time.
- Matching each payment to the correct member.
- Keeping records for queries and reconciliation.
- Managing the safety concerns linked to holding or moving cash.
These tasks become more complex as membership grows. An incorrect amount or incomplete record can also lead to disputes, even when the mistake is unintentional.
A digital payout process creates a clear transaction trail. A transaction record for every payout gives administrators a clear view of completed and outstanding payments. This does not remove the need for sound governance, but it can make day-to-day control simpler.
How MyMoolah’s single API transforms stokvel operations
A fragmented digital model may require one provider for disbursements and separate integrations for services such as airtime or electricity. Each extra connection can add technical and administrative work.
MyMoolah brings wallet disbursements and value-added services, or VAS, together through a single API. A stokvel platform, association or fintech partner can use that integration to build a more connected member experience.
Instant disbursements to members
Administrators can initiate payouts to members’ MyMoolah digital wallets through the disbursement API.1 This removes the need to prepare physical cash or make conventional bank transfers for each payout.
For the administrator, digital records support faster tracking and reconciliation. For the member, funds are available in a wallet and can be used through the supported payment and value-added service channels. Members who still need cash can cash out with a bank-issued cardless withdrawal PIN, where available.1
Earn more with value-added services
The same API offers access to airtime, mobile data and electricity purchases. These services create a commission-earning opportunity for stokvel administrators or partners.1
This means the operating model does not need to end with a payout. A participating member may choose to use wallet funds for an everyday service, while the administrator can earn commission from qualifying VAS activity. No commission rate or level of income should be assumed: actual commercial terms must be agreed with MyMoolah.
The value is in combining two functions:
- Operational value: fewer manual payout steps and less cash handling.
- Commercial value: an opportunity to earn commission when members buy supported value-added services.
An illustrative use case: stokvel payouts and VAS in action
Consider a stokvel that makes scheduled payouts to its members. Under a manual process, the administrator may need to prepare cash, arrange collection or process separate transfers.
With a MyMoolah integration, the process could work as follows:
- The stokvel confirms the approved payout list and amounts.
- The connected platform initiates wallet disbursements through the API.
- The administrator tracks the transactions and uses the dashboard records for reconciliation.
- Members receive their funds in their digital wallets.
- A member can keep the funds digital, buy airtime, data or electricity, make a supported QR payment, or use an available cash-out option.
- The stokvel administrator or partner has an opportunity to earn commission from supported VAS purchases, subject to agreed commercial terms.
This is an illustrative workflow, not a claim about the results of a specific stokvel. The actual setup will depend on the partner’s platform, operating rules and agreed integration scope.
Security and compliance on regulated payment infrastructure
Confidence matters when members move from cash to digital wallets. MyMoolah is a registered Third-Party Payment Provider (TPPP) sponsored by The Standard Bank of South Africa Limited.1 MyMoolah is not a bank, and this status does not mean that it is affiliated with the South African Reserve Bank.
Wallet security features include PIN protection and transaction limits. MyMoolah also applies compliance and data protection measures. Administrators should support these controls with clear member education, secure access procedures and defined processes for payment queries.
MyMoolah wallet holders can pay by QR at participating retailers. The SARB published QR+ Standard 1.2 on 7 July 2026, showing the direction of South Africa’s interoperable digital payment infrastructure.2 This does not give MyMoolah special access to SARB systems or imply a partnership with the SARB.
A gradual path from cash to digital payments
Some members may be cautious about digital wallets because of fraud concerns or a preference for cash. A gradual rollout can help administrators respond to these concerns without disrupting the stokvel’s established way of working.
Useful steps can include explaining PIN safety, setting clear payout procedures and showing members how to check transactions. Cash-in and cash-out services can remain part of the model while members become more comfortable with digital payments.
This blended approach gives members choice. It also allows the stokvel to gain the record-keeping and payout benefits of digitisation without treating cash and digital channels as an all-or-nothing decision.
Simpler onboarding for partners and stokvels
A single API can reduce the number of technical connections needed for wallet disbursements and VAS. Before launch, partners should define the payout workflow, member support process, reconciliation roles, access controls and VAS commercial terms.
Administrators should also decide how members will be informed about wallet use, transaction limits, PIN security, cash access and available services. Clear communication is as important as the technical integration.
Getting started with MyMoolah
Stokvels, associations, channel partners and fintech platforms can begin by mapping their current payout process. Identify the manual steps, control gaps and member needs that a digital model should address. The next step is to assess how wallet disbursements, cash access and VAS can fit into one operating flow.
Sources:
- 1 MyMoolah business profile supplied for this article.
- 2 South African Reserve Bank, QR+ Standard 1.2, published 7 July 2026.
Ready to offer wallet services with disbursements + VAS via a single API integration? Contact partnerships@mymoolah.africa